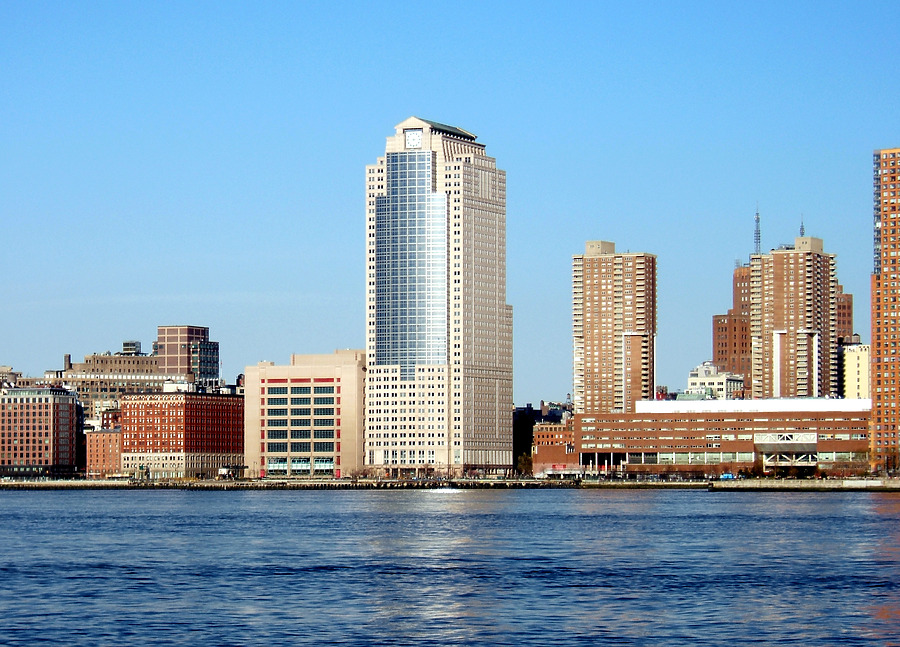
388 Greenwich Street New York: How One Address Anchors a Global Financial Powerhouse
388 Greenwich Street New York: How One Address Anchors a Global Financial Powerhouse
At the crossroads of finance, technology, and urban energy, 388 Greenwich Street in New York stands as a quiet epicenter of market-moving activity. This Midtown tower hosts some of the world’s largest asset managers and trading firms, turning a single address into a node of global capital flows. More than a mailing address, it serves as a physical anchor for a digital infrastructure ecosystem that never sleeps.
The building at 388 Greenwich Street, completed in the late 1980s and extensively renovated in the 2010s, sits within a dense knot of exchanges, data centers, and legal institutions. Its location a few blocks from the New York Stock Exchange and a short walk from major fiber routes gives it outsized importance for high-frequency trading and low-latency strategies. For traders, engineers, and compliance teams, the address is a shorthand for proximity, reliability, and speed.
Proximity is not just geographic; it is temporal. In markets where microseconds can determine the outcome of a trade, firms cluster around aging conduits of connectivity housed in aging but meticulously maintained infrastructure. 388 Greenwich Street functions as a layered node where price discovery, risk management, and execution converge. The result is a compressed map of capitalism, redrawn not in countries but in fiber spans and server racks.
A critical mass of buy-side firms has taken root in the tower, turning the address into a hub for portfolio management, risk analytics, and direct market access. The density of decision-making under one roof amplifies feedback loops, where price movements in Tokyo ripple through to London and then bounce off trading desks in New York before the close of the U.S. session.
Inside the building, operations follow a choreography dictated by global time zones. Morning routines in Asia feed into afternoon volatility in Europe, which in turn collide with the opening bells in New York. Traders stationed at 388 Greenwich Street operate at the fulcrum of this rhythm, balancing screens that display order books, news feeds, and risk metrics in real time.
For many asset managers, the address represents a carefully curated ecosystem of counterparties. Custodians, clearing firms, and data vendors sit within the same corridor or adjacent towers, enabling last‑minute adjustments to hedges and facilitating same‑day settlements. The convenience is not incidental; it is engineered into the site’s legal jurisdiction, telecommunications infrastructure, and regulatory oversight.
The technology backbone that supports these activities is both invisible and immense. Multiple fiber strands enter the building from different directions, creating redundant paths to exchanges and data providers across the tri-state region. Microwave and satellite links supplement terrestrial fiber for certain time‑sensitive flows, while colocation cages inside the tower house servers that execute algorthims close to the matching engines of the exchanges.
One quant strategist who works in the building described the logic of concentration this way: “You want to be close to where the information lives and where the liquidity aggregates. At 388 Greenwich, the latency advantages are real, but so is the network effect of being surrounded by people solving the same problems.” The comment underscores how physical proximity translates into informational advantage in a landscape defined by speed.
Regulatory scrutiny has intensified around precisely these clusters of algorithmic trading and high‑frequency market making. Authorities in the United States and abroad have examined whether proximity-based advantages create systemic risks or distort price formation. In response, firms at 388 Greenwich Street have invested in compliance technology, from real‑time surveillance systems to audit trails capable of reconstructing every decision in a order’s life cycle.
Cybersecurity is another frontline concern. The concentration of capital and data in a single address makes the building a target for both digital intrusion and physical threat. Property managers and tenants conduct regular drills, collaborate with local law enforcement, and harden network perimeters with next‑generation firewalls, intrusion detection systems, and zero‑trust access controls.
Operational resilience has taken on new meaning in a world where outages at one node can ripple through interconnected markets. Firms maintain failover sites in other parts of Manhattan and in neighboring regions, ensuring that if one data center falters, orders can be rerouted without catastrophic delay. The address at 388 Greenwich Street is therefore part of a larger lattice of redundancy, not a solitary bastion of activity.
The human dimension of this infrastructure is equally complex. Traders, engineers, and operations staff work in shifts that blur the line between day and night. Cafeterias fill early in the morning as Asian equity traders arrive, while European bond specialists appear mid‑day, and U.S. equity and derivatives teams take over the floor as the sun sets. The building thus functions as a 24-hour organism, sustained by coffee, code, and constant communication.
Sustainability has entered the conversation as newer towers compete on energy efficiency and lower carbon footprints. Tenants at 388 Greenwich Street are weighing upgrades to cooling systems, server efficiency, and renewable power purchases, balancing the demands of performance with the expectations of environmental, social, and governance-conscious investors. The shift is incremental but indicative of how even the most established addresses must evolve.
Technological upgrades occur in waves, driven by changes in market structure, new asset classes, and evolving client demands. Firms routinely refresh their hardware, migrate workloads to more efficient infrastructure, and retrain staff on emerging tools. What remains constant is the calculus that places premium value on a location that offers speed, stability, and access.
In the background, commercial real estate dynamics quietly shape the scene. Lease expirations, sublet availability, and shifting demand from hedge funds, family offices, and proprietary trading desks influence who occupies the space and how it is used. The presence of anchor tenants lends stability, while nimble newcomers bring experimentation and, occasionally, disruption.
Across the street and in nearby buildings, a parallel financial district has emerged, one built not only on brick and steel but on packets, protocols, and legal agreements. Arbitration clauses, service of process rules, and jurisdictional preferences are as important as millisecond advantages in determining where capital chooses to reside. For many firms, 388 Greenwich Street hits the sweet spot between accessibility and protection.
The global financial system has become more concentrated yet more distributed, and addresses like this one embody that paradox. Trading rooms may shrink as cloud computing expands, but the pull of dense connectivity persists. 388 Greenwich Street endures as a testament to the stubborn importance of place, even in an era that often claims distance has been abolished.
Clients rarely see the building, yet its influence reaches outward through every executed order, settled trade, and reported metric. Behind the calm facade lies a nervous system of cables, algorithms, and human decisions, all aligned in the pursuit of moving capital with precision. In that sense, the address is less a point on a map than a node in a living network.
Looking ahead, the building will likely host technologies not yet imagined, from quantum-resistant encryption to AI-driven risk models. The fundamentals, however, remain unchanged: speed, trust, and proximity continue to govern how capital flows, and 388 Greenwich Street remains positioned at the center of that equation. For those who operate within its walls, the view from the windows is less a panorama than a reminder of how many layers of the financial world can converge in a single address.
Related Post