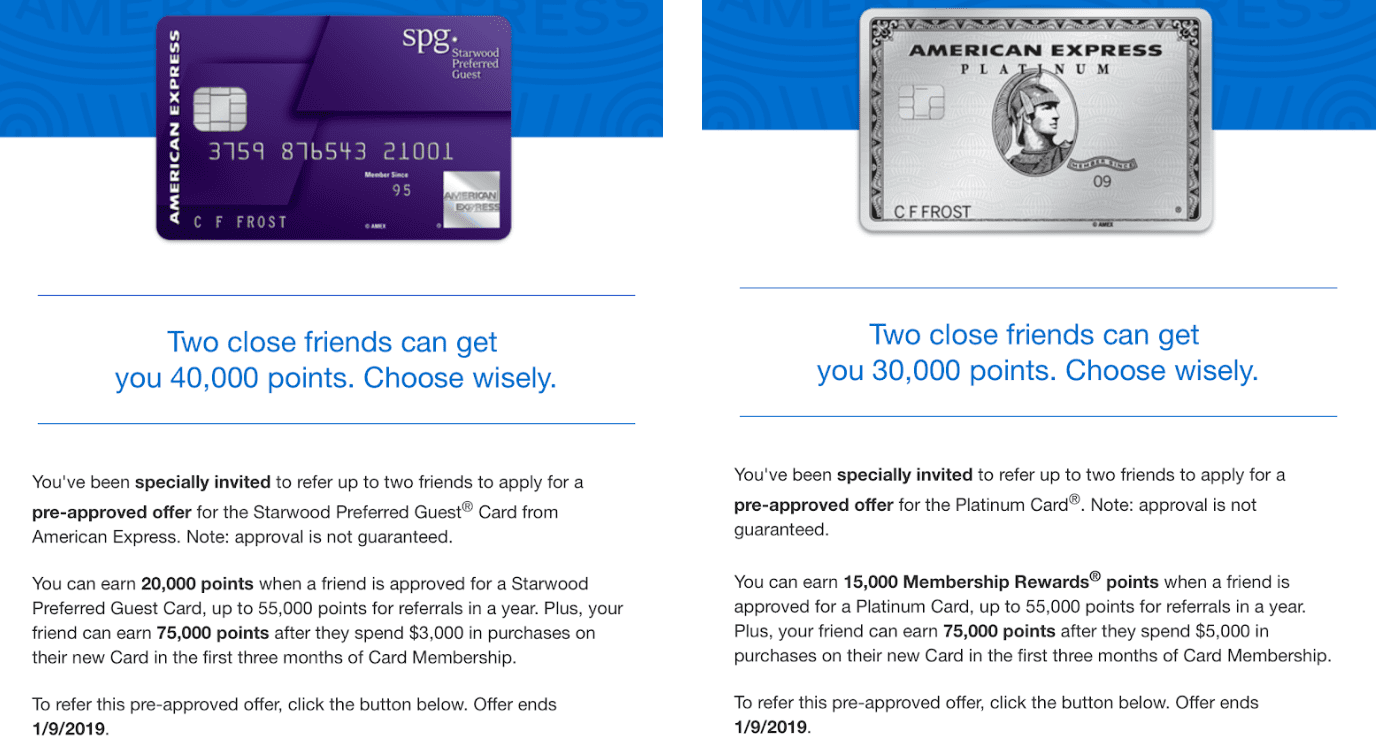
Amex Pre Approval Decoded: How It Works, Eligibility, and Whether It’s Worth It
Amex Pre Approval Decoded: How It Works, Eligibility, and Whether It’s Worth It
American Express pre-approval is a targeted, soft-credit-check offer that signals you meet key criteria for specific cards. It provides a low-friction path to card ownership but does not guarantee final approval once a formal application is submitted. This article explains the mechanics, benefits, limitations, and strategic considerations of Amex pre-approval for consumers and advisors.
Many cardholders first encounter the concept of pre-approval through uninvited email snippets or notifications in the Amex app that read, "You may pre-qualify." This seemingly small cue can influence spending decisions and credit strategies, yet its underlying rules are opaque. Understanding what pre-approval represents—and what it does not—is essential for interpreting these signals accurately.
Pre-approval is not a binding promise of credit; rather, it is an initial eligibility assessment based on a soft inquiry and high-level financial indicators. It is designed to streamline the path to approval while protecting both the consumer and the issuer from unnecessary hard pulls. The following sections break down the mechanics, advantages, and risks of Amex pre-approval in detail.
Amex pre-approval typically originates from one of two sources: proactive outreach based on internal models or user-initiated checks via the Amex website or app.
- Internal evaluation: Amex uses proprietary scoring models to identify accounts in good standing that may qualify for other products. A soft pull, which does not affect your credit score, is often employed to confirm basic creditworthiness without a full review.
- Consumer check: Cardmembers can check pre-approval status in their online account or app under offers or membership criteria. These checks also usually involve a soft inquiry.
- Offer curation: Pre-approved offers are tailored to your spending patterns, payment history, and relationship with Amex. If your behavior aligns with the profile for a premium card, you may see targeted invitations.
The pre-approval process is best understood as a conditional pass. It indicates a high probability of approval but stops short of guaranteeing it. Because a full review only occurs after you formally apply, pre-approval should not be conflated with final credit approval.
Various Amex products may be surfaced through pre-approval, depending on your profile. The range typically spans charge cards, credit cards, and co-branded options.
- Charge cards: Offers like the American Express® Gold Card or Business Gold Card often appear for users with strong spending and payment histories.
- Credit cards: Certain unsecured personal cards may be presented as accessible options for those building or rebuilding credit.
- Co-branded cards: Retail or airline co-branded cards frequently appear as pre-approved offers, especially if you demonstrate relevant spending categories.
Each offer is tied to specific terms, including fees, APR ranges, and introductory benefits. It is important to read the full terms before accepting, as advertised benefits may not apply universally.
The strategic value of pre-approval depends on your immediate goals and risk tolerance. For some, it serves as a planning tool; for others, it is a shortcut to accessing premium benefits.
- Soft-check awareness: You can gauge product eligibility without impacting your credit score, allowing for informed decision-making.
- Faster onboarding: Pre-approved applicants often experience a streamlined application process with reduced manual review.
- Targeted benefits: Offers are curated to match your spending behavior, increasing the likelihood that you will derive value from them.
However, pre-approval is not without caveats. Because it is based on a limited dataset, it does not capture the full financial picture. Income, debt obligations, and recent credit applications are among the factors that may not be fully reflected in a soft-check model.
Approvals can still be declined during the underwriting phase, which may be triggered by a hard pull at the application stage. This discrepancy can be confusing, but it underscores the conditional nature of pre-approval.
The language surrounding pre-approval can sometimes create confusion. Some consumers assume pre-approval equals guaranteed credit, while others dismiss it as mere marketing. Clear definitions help align expectations with reality.
- Pre-qualification: A preliminary screening based on very limited data, often used for marketing outreach. This step typically relies on a soft check and broad assumptions about credit behavior.
- Pre-approval: A more refined indication of eligibility that considers slightly more robust criteria, though still not a final review.
- Final approval: The outcome of a full underwriting process, which may include a hard pull and comprehensive assessment of financial documents.
Understanding these distinctions clarifies why a pre-approval offer can evolve into a rejection upon formal application. It also highlights the importance of reviewing your credit health and financial readiness before proceeding.
When evaluating an Amex pre-approval offer, consider both the opportunity and the obligations it entails. A structured assessment can prevent missteps and align decisions with long-term goals.
- Review the product terms carefully: Annual fees, interest rates, and benefit structures should be compared against similar products in the market.
- Assess your credit impact: While a pre-approval check is typically a soft inquiry, submitting the application moves to a hard pull, which can temporarily lower your score.
- Evaluate your financial capacity: Ensure that you can meet minimum payment requirements and manage the card within your budget.
- Monitor approval outcomes: If you choose to apply, track the status and be prepared to provide additional documentation if requested.
If you receive a pre-approval offer but are not ready to apply, you can usually opt out of targeted offers through Amex’s preference settings or national opt-out programs. This reduces unsolicited invitations without affecting your existing accounts.
For advisors and professionals, explaining pre-approval within the broader context of credit management adds clarity for clients. It transforms a potentially confusing notification into a teachable moment about responsible credit use.
- Credit literacy: Teach clients that pre-approval is an estimate, not a guarantee, and that understanding underwriting criteria can empower better decisions.
- Strategic planning: For those optimizing credit mix or preparing for large purchases, pre-approval can inform timing and product selection.
- Risk management: Emphasize the importance of reading terms thoroughly and avoiding unnecessary hard pulls that could affect future lending opportunities.
American Express pre-approval is a tool that, when used thoughtfully, supports informed credit decisions. It offers a window into potential opportunities while emphasizing the importance of due diligence. By understanding how it works and what it represents, consumers and professionals can navigate credit offers with greater confidence and clarity.
Related Post