The Cenlar Mortgage Conundrum: Inside The National Housing Debate On Loan Servicing And Accountability
The Cenlar Mortgage Conundrum: Inside The National Housing Debate On Loan Servicing And Accountability
Across the United States, homeowners facing financial strain are discovering that the complexity of mortgage servicing can be as daunting as the housing market itself. Cenlar Mortgage, a major player in the loan servicing industry, finds itself at the heart of this intricate system, managing millions of accounts on behalf of investors. This article examines the role Cenlar Mortgage plays in the housing finance ecosystem, the regulatory scrutiny it has faced, and the real-world impact on borrowers navigating the often-opaque world of loan administration.
The mortgage landscape is divided between entities that originate loans and those that service them, and Cenlar Mortgage is a prime example of the latter. Unlike a bank that might hold a loan from inception, a mortgage servicer like Cenlar acquires the rights to service existing loans, collecting monthly payments, managing escrow accounts, and handling customer inquiries. According to data from the Federal Housing Finance Agency, the mortgage servicing rights (MSR) market represents a significant segment of the financial industry, with servicers acting as the critical interface between Wall Street investors and Main Street homeowners. Cenlar, headquartered in Omaha, Nebraska, has grown to become one of the largest pure-play servicers in the nation, managing approximately 3.5 million residential mortgage accounts as of recent reports. Its business model hinges on performing these administrative tasks for a fee, a structure that has drawn both praise for its efficiency and criticism for its perceived detachment from the borrowers it impacts.
The mechanics of mortgage servicing involve a wide array of responsibilities that extend far than merely accepting checks or electronic transfers. When a borrower makes a payment to Cenlar Mortgage, the funds are first applied to interest, then to principal, with various fees deducted along the way. The servicer must also handle property tax and homeowners insurance payments placed into an escrow account, track payment histories, and manage the complex process of loan workouts or modifications for distressed borrowers. Cenlar, like its competitors, utilizes sophisticated software systems to manage these tasks, but the human element remains crucial, particularly when errors occur or borrowers seek assistance. Industry analyst Michele Greppi notes, "The servicer is the face of the loan, and when things go wrong, the borrower's frustration is directed at that institution, regardless of who actually owns the underlying mortgage note." This places a significant burden on servicers to maintain accurate records and responsive customer service, even as they operate under intense profit pressures and regulatory obligations.
Over the past decade, Cenlar Mortgage has faced its share of legal and regulatory challenges that highlight the tensions within the servicing model. The Consumer Financial Protection Bureau (CFPB) and state attorneys general have launched numerous investigations into alleged servicing abuses, including errors in foreclosures, mishandling of loss mitigation applications, and difficulties in reaching customer service representatives. In 2014, Cenlar reached a multi-state settlement related to foreclosure practices, agreeing to provide millions of dollars in restitution to borrowers and implement improvements to its processes. More recently, the company has been involved in addressing issues related to pandemic-era forbearance programs, where a surge in requests for payment relief exposed systemic vulnerabilities in the servicing infrastructure. A spokesperson for Cenlar stated in a recent interview, "We are committed to regulatory compliance and continuously reviewing our processes to ensure we are meeting our customers' needs and adhering to the highest standards of conduct." This commitment, however, is often tested by the sheer volume of accounts and the inherent ambiguities in housing regulations.
The impact of Cenlar's operations is felt most acutely by the individual homeowners who interact with its systems. For borrowers, the servicer relationship can be a source of significant stress, particularly during major life events such as job loss, medical emergencies, or divorce. The process of applying for a loan modification, for instance, can require extensive documentation and patience, as requests move through various departments within the servicing company. Errors in accounting or communication can lead to wrongful foreclosures or prolonged financial hardship, eroding trust in the entire system. Consider the case of a hypothetical borrower, "Sarah," who loses her job and contacts Cenlar to explore forbearance options. She may be transferred between multiple customer service agents, asked to resubmit the same documents, and receive conflicting information about her eligibility. Such experiences, repeated across thousands of borrowers, contribute to a widespread perception that the servicing industry is more focused on procedural compliance than on empathetic customer resolution.
In response to these challenges, the mortgage servicing industry, including Cenlar, has begun to adopt technological innovations aimed at improving accuracy and customer experience. Automation and artificial intelligence are being deployed to streamline payment processing, identify potential errors earlier, and provide borrowers with more transparent online account management tools. Cenlar has invested in updated customer relationship management platforms and has expanded its digital offerings to allow for more self-service options. However, technology is not a panacea. The transition to digital processes can create new barriers for elderly or less tech-savvy borrowers, and algorithmic decision-making systems can sometimes lack the nuance required for complex individual circumstances. Legal scholar David Stevens argues, "The future of servicing lies in balancing technology with human oversight. The goal should be to use data to prevent problems, not just to resolve them faster after the fact." This evolving landscape suggests that the role of Cenlar and similar servicers will continue to transform, shaped by regulatory mandates, technological advancement, and the ongoing demands of a diverse borrower population.
Looking ahead, the relationship between Cenlar Mortgage and the homeowners it serves will remain a focal point of public policy and public scrutiny. As the housing market continues to fluctuate and new economic pressures emerge, the effectiveness of the servicing model will be tested repeatedly. For Cenlar, the path forward involves not only navigating regulatory requirements but also rebuilding trust through demonstrable improvements in accuracy, communication, and fairness. The company’s long-term success will depend on its ability to recognize that behind every account number is a real person with a financial stake and often a significant emotional investment. The broader industry must also adapt, ensuring that the critical function of mortgage administration serves to stabilize the housing market rather than undermine it, providing a reliable and transparent bridge between the assets on Wall Street and the homes that define lives on Main Street.
Related Post
Cenlar Mortgage Login: The Definitive User Guide to Account Access and Management
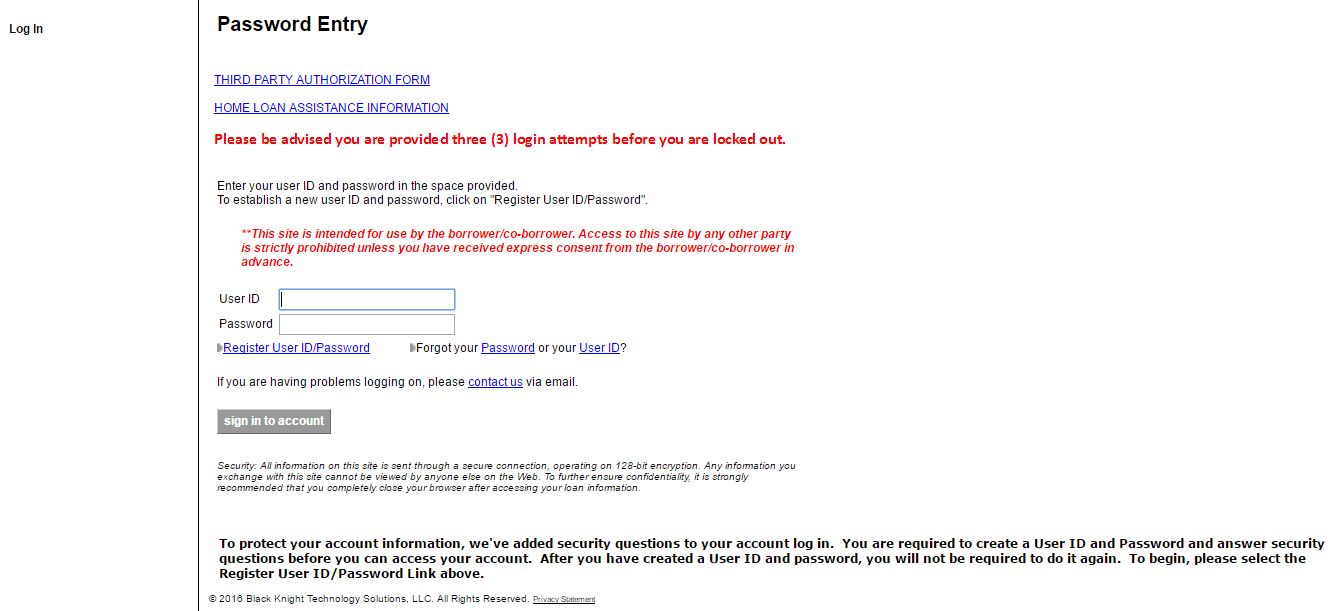
Unlocking the Power of Cenlar Mortgage Loan Login: A Comprehensive Guide
Cenlar Mortgage Login: Your Easy Access Guide


