The Comenity Bank Ulta Credit Card: A Deep Dive into Benefits, Credit Impact, and Account Management
The Comenity Bank Ulta Credit Card: A Deep Dive into Benefits, Credit Impact, and Account Management
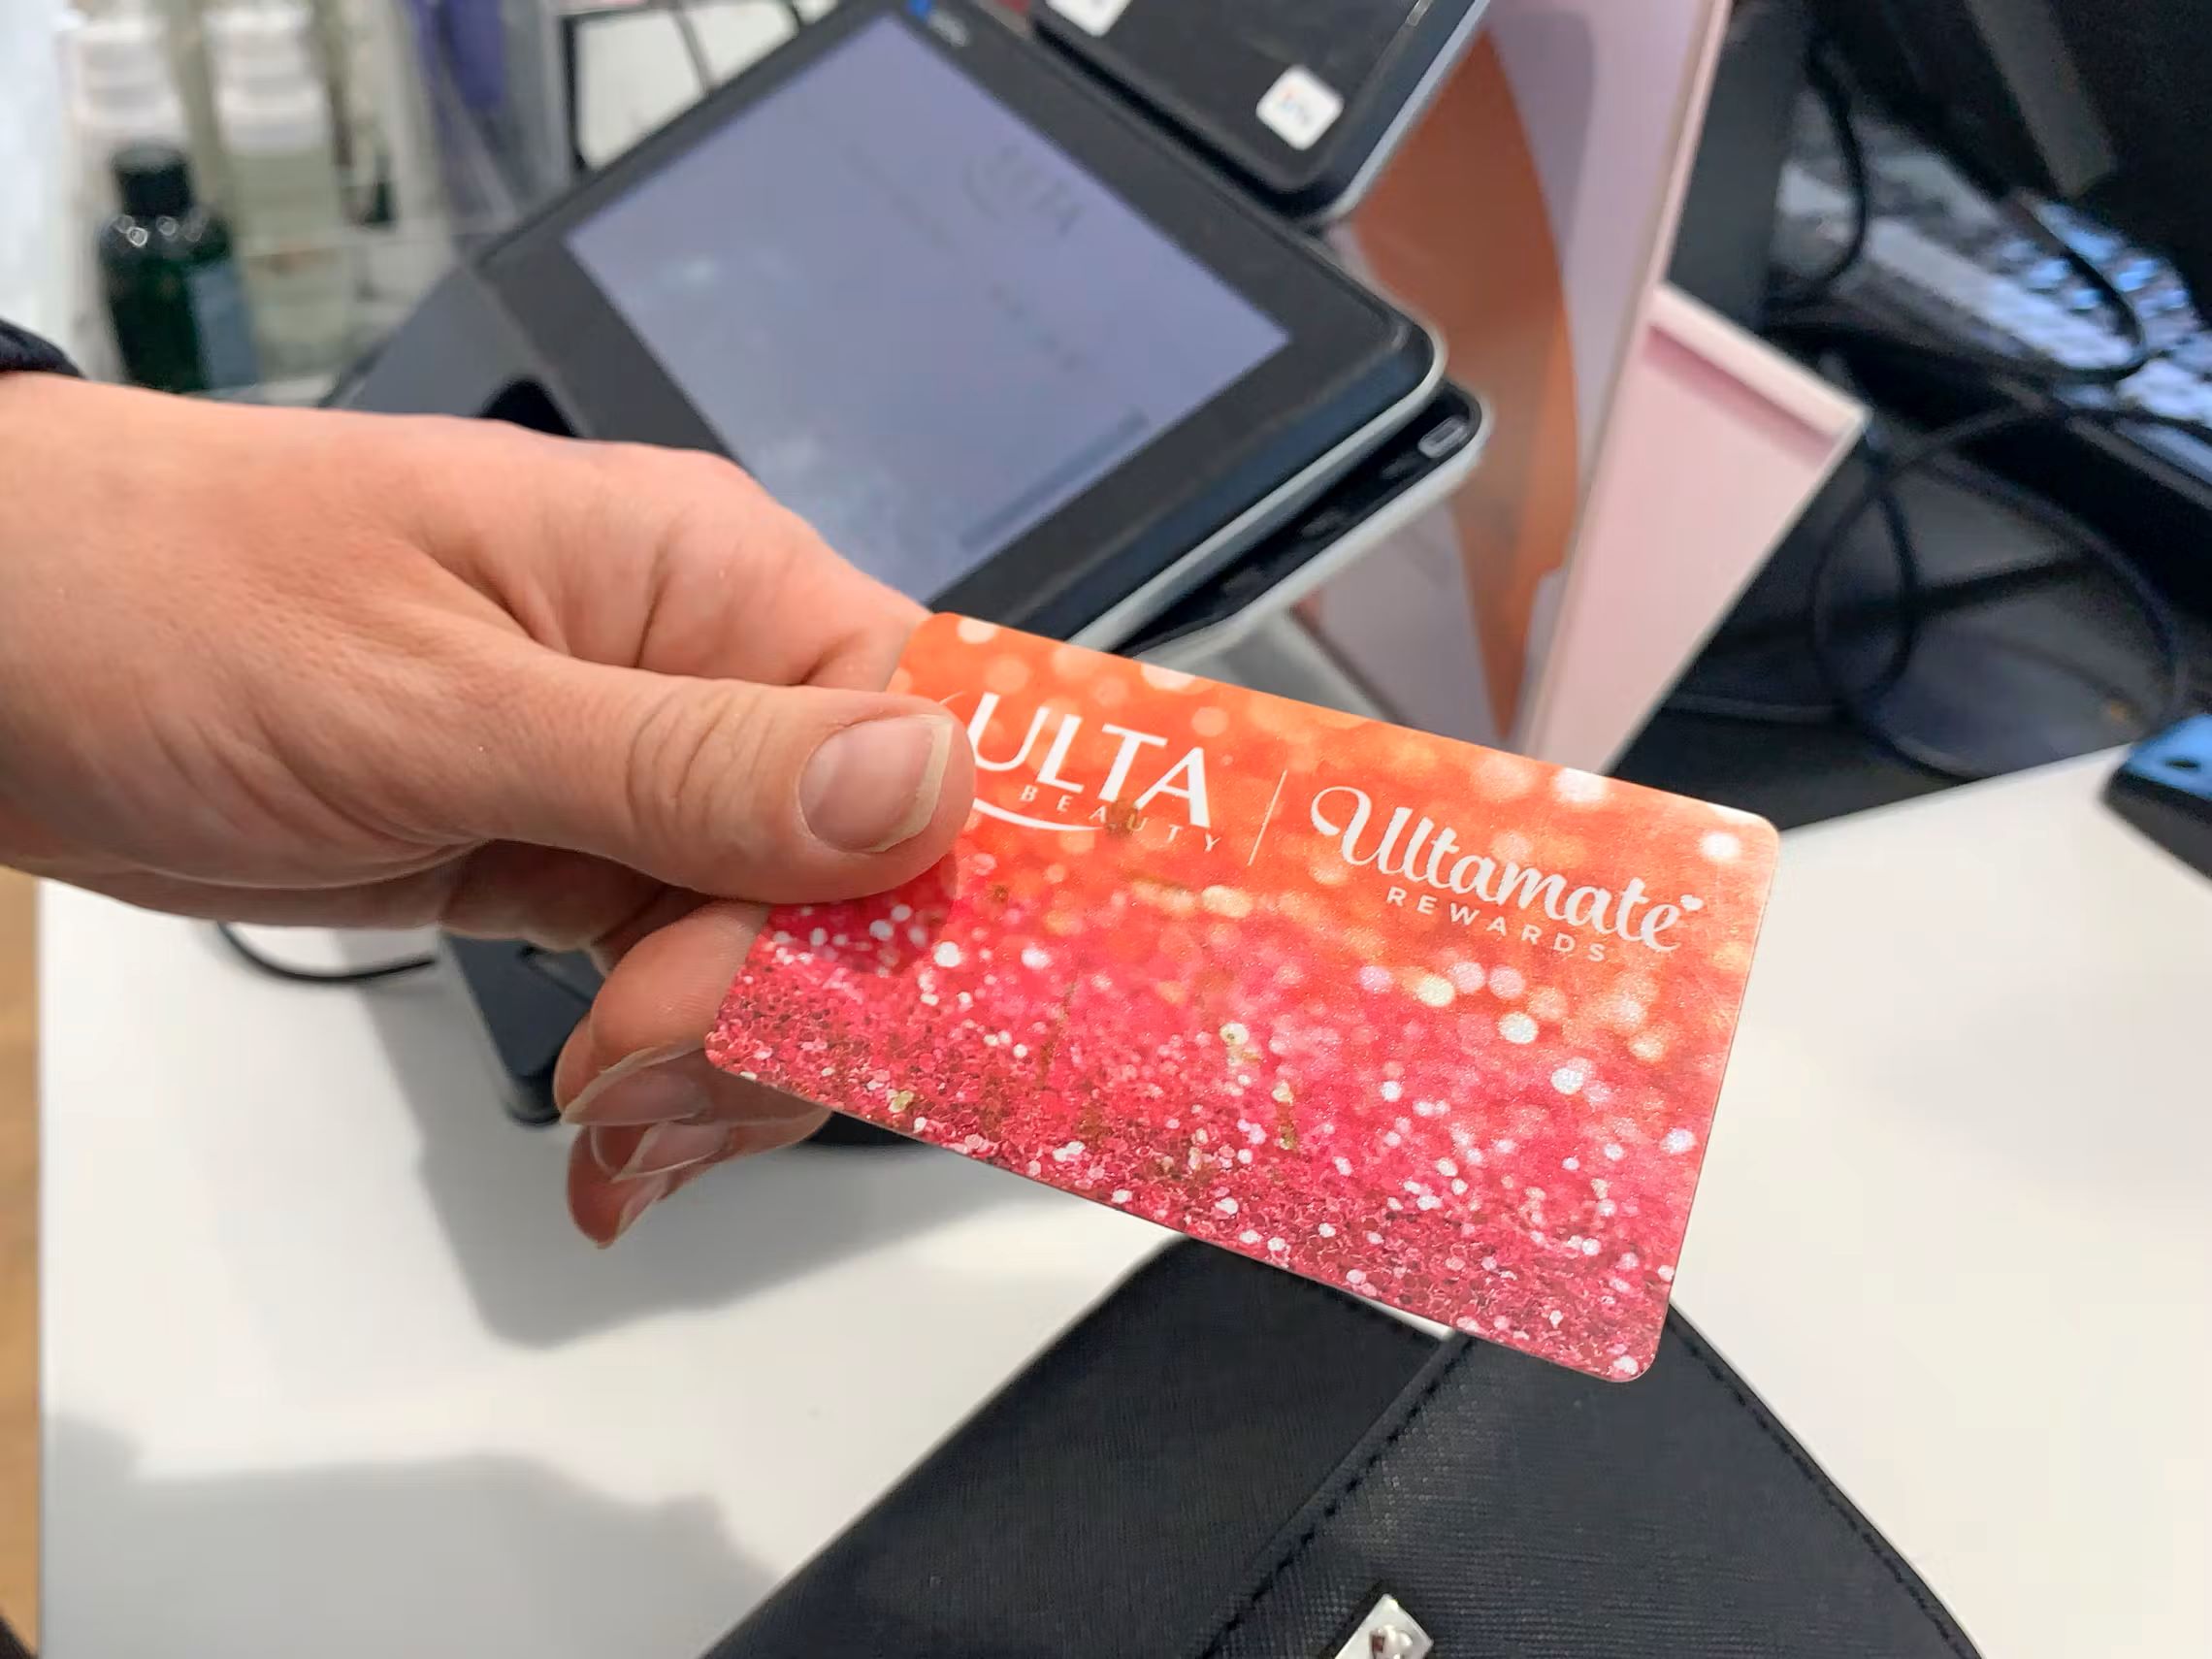
The Comenity Bank Ulta credit card is a specialized retail product issued by Comenity Bank, catering specifically to beauty and wellness shoppers at Ulta Beauty. This card offers targeted rewards within the beauty ecosystem, but it also carries the standard risks and responsibilities of any revolving credit account. Understanding the intricate relationship between Comenity Bank, Ulta, and the consumer is essential for maximizing value while maintaining healthy credit habits.
For years, Ulta Beauty has relied on strategic partnerships to power its loyalty and credit programs. Comenity Bank, a veteran issuer specializing in retail and specialty cards, manages the financial backend of the Ulta credit card portfolio. This arrangement allows Ulta to focus on merchandising and customer experience while leveraging Comenity’s decades of expertise in credit risk assessment and account servicing. The card represents a financial tool designed to incentivize spending within a specific vertical, but it functions like any other bank-issued credit card in the hands of the consumer.
This article provides a comprehensive, objective look at the Comenity Bank Ulta card. We will explore the specific benefits offered to cardholders, analyze how the card impacts credit scores, and detail the processes for account management, payments, and customer service interactions. By separating marketing claims from financial realities, we aim to equip current and prospective cardholders with the information needed to make informed decisions.
### The Mechanics of the Partnership: Comenity Bank and Ulta
The relationship between Comenity Bank and Ulta is a classic example of a bank-program manager partnership. Comenity Bank is not a new or obscure financial entity; it is a seasoned issuer with a long history of managing private label credit cards for major retailers. When a customer applies for an Ulta card, they are ultimately applying for a credit line extended by Comenity Bank, even though the card bears the Ulta logo and can only be used at Ulta stores and online.
This structure dictates nearly every aspect of the cardholder experience. The terms of the agreement, including the Annual Percentage Rate (APR), fee structures, and credit reporting practices, are determined by Comenity Bank. Ulta’s role is primarily in marketing the card and integrating it into their loyalty ecosystem. As a former executive in the retail financial space noted, "The partnership allows brands like Ulta to monetize their customer base through credit while mitigating the operational burden and regulatory complexities of banking." The brand provides the customer base and the shopping environment, while the bank provides the capital and the regulatory compliance.
For the consumer, this means that your interactions are primarily with two entities: Ulta for redemptions and general inquiries, and Comenity Bank for all financial matters. This distinction is crucial when seeking support or attempting to manage your account. You are a borrower from Comenity Bank, not a customer of Ulta in the credit transaction sense.
### Benefits and Rewards: What the Card Actually Offers
The primary allure of the Comenity Bank Ulta card is its tiered rewards structure, which is explicitly designed to drive revenue and loyalty for the beauty retailer. The card typically operates on a points-based system where every dollar spent generates a specific number of Ultamate Rewards points. However, the value of these points is intrinsically linked to the retailer.
* **Earning Structure:** Cardholders generally earn 5 points for every dollar spent at Ulta and 1 point for every dollar spent elsewhere. This structure incentivizes shoppers to consolidate their beauty purchasing at Ulta to maximize point accrual.
* **Reward Redemption:** Points are redeemed exclusively within the Ulta ecosystem. They can be used to offset future purchases, effectively functioning as a store credit. The appeal of this system is its simplicity and direct applicability. If you are a regular Ulta shopper, the points you accumulate will almost certainly be used on future beauty products.
* **Financing Offers:** Like many retail credit cards, the Ulta card is frequently marketed with promotional financing options, such as "6 months same as cash" on purchases over a certain amount. While these offers can be financially advantageous if the balance is paid off in full within the promotional period, they can become traps if the balance carries over, as the deferred interest can capitalize abruptly.
It is important to view these benefits through a critical lens. The value of the card is entirely dependent on the cardholder's shopping frequency at Ulta. For a frequent Ulta shopper, the card can be a significant source of savings and rewards. For an infrequent shopper, the card is likely to be a dormant asset that provides little benefit and may pose an unnecessary credit inquiry and potential debt risk.
### Impact on Credit: Scores, Inquiries, and Utilization
Applying for and maintaining a Comenity Bank Ulta card has tangible effects on your credit profile, both positive and negative. The first and most immediate impact is the hard inquiry that occurs when you submit your application. This inquiry can cause a small, temporary dip in your credit score, typically lasting a few points and fading within a few months.
Once the account is opened, its long-term impact depends on how it is managed. Payment history is the single most important factor in credit scoring. Making timely payments is paramount. A late payment on an Ulta card can remain on your credit report for seven years and will damage your score significantly.
The card also affects your credit utilization ratio, which is the amount of credit you are using compared to your total available credit. This ratio is a major component of your credit score. If you hold the Ulta card as your only credit line, maxing it out will severely hurt your score. However, if you have a healthy mix of credit and keep your balance low relative to your limit, the card can contribute positively to your score over time. As a credit analyst often explains, "Any credit card is merely a tool. Whether it builds or breaks your credit depends entirely on the user's discipline in managing that tool."
### Account Management and Customer Service Realities
Managing your Comenity Bank Ulta account requires navigating a specific set of protocols. Since Comenity Bank is the issuer, all account-related functions—payments, balance checks, spending limits, and dispute resolution—are handled through Comenity’s systems, not Ulta’s.
For bill payments, cardholders have several options. You can typically pay online through the Comenity Bank portal, set up automatic payments, or mail a check to the address provided on your statement. The key is to ensure payments are processed well before the due date to avoid late fees and negative reporting.
Customer service for account-specific issues will direct you to Comenity Bank. If you have a question about your statement, a transaction dispute, or need to change your payment information, you will be interacting with Comenity’s call center. While Ulta customer service is excellent for product-related questions, they generally cannot access or modify your credit account details. This separation can sometimes be a point of frustration for consumers who expect a unified retail-bank experience. Understanding that the bank is the lender and the issuer of the account terms is the first step in navigating these interactions effectively.
Related Post