The Hidden Mechanics of RBC Online: How Digital Banking Reshapes Financial Behavior
The Hidden Mechanics of RBC Online: How Digital Banking Reshapes Financial Behavior
Digital banking has moved from convenience to necessity, and RBC Online stands at the center of that shift for millions of Canadian clients. By translating traditional branch services into a responsive, algorithm-driven interface, the platform changes not only how people manage money but also how they perceive risk, reward, and time. This report explores the architecture, incentives, and behavioral consequences of banking online through RBC’s portal, drawing on public data, policy documents, and observable patterns of use.
RBC Royal Bank launched its digital banking initiative more than a decade ago, but the pace of change accelerated during the pandemic as physical branches closed and mobile usage surged. What began as a portal for balance checks and bill payments has evolved into a complex ecosystem of credit decisions, investment prompts, and data monetization. Understanding RBC Online requires looking beyond the user interface and into the rules, incentives, and data flows that shape every click.
The technical backbone of RBC Online rests on a layered architecture that connects client devices, secure data centers, and external networks. Encryption protocols, multi-factor authentication, and continuous monitoring form the baseline defenses, yet the system’s design also nudges users toward specific behaviors. For example, automated savings tools and credit limit prompts appear at moments when engagement is highest, often after a user logs in to check a balance or transfer funds.
- Application programming interfaces allow third-party services to interact with RBC Online under strict security rules, expanding the platform’s reach while increasing surveillance capabilities.
- Real-time analytics track session duration, click paths, and hesitation points, enabling the bank to refine prompts and offers continuously.
- Fail-safes such as transaction alerts and spending thresholds aim to protect users, but they also generate data streams that feed risk models.
From a regulatory perspective, RBC Online operates under the same rules that govern physical branches, but enforcement lags behind technological innovation. Canadian financial authorities have issued guidelines on transparency, data use, and algorithmic bias, yet critics argue that these rules rarely keep pace with new features. A 2022 report by the Office of the Superintendent of Financial Institutions emphasized the need for “dynamic oversight” frameworks that can adapt to rapidly evolving digital services without stifling innovation.
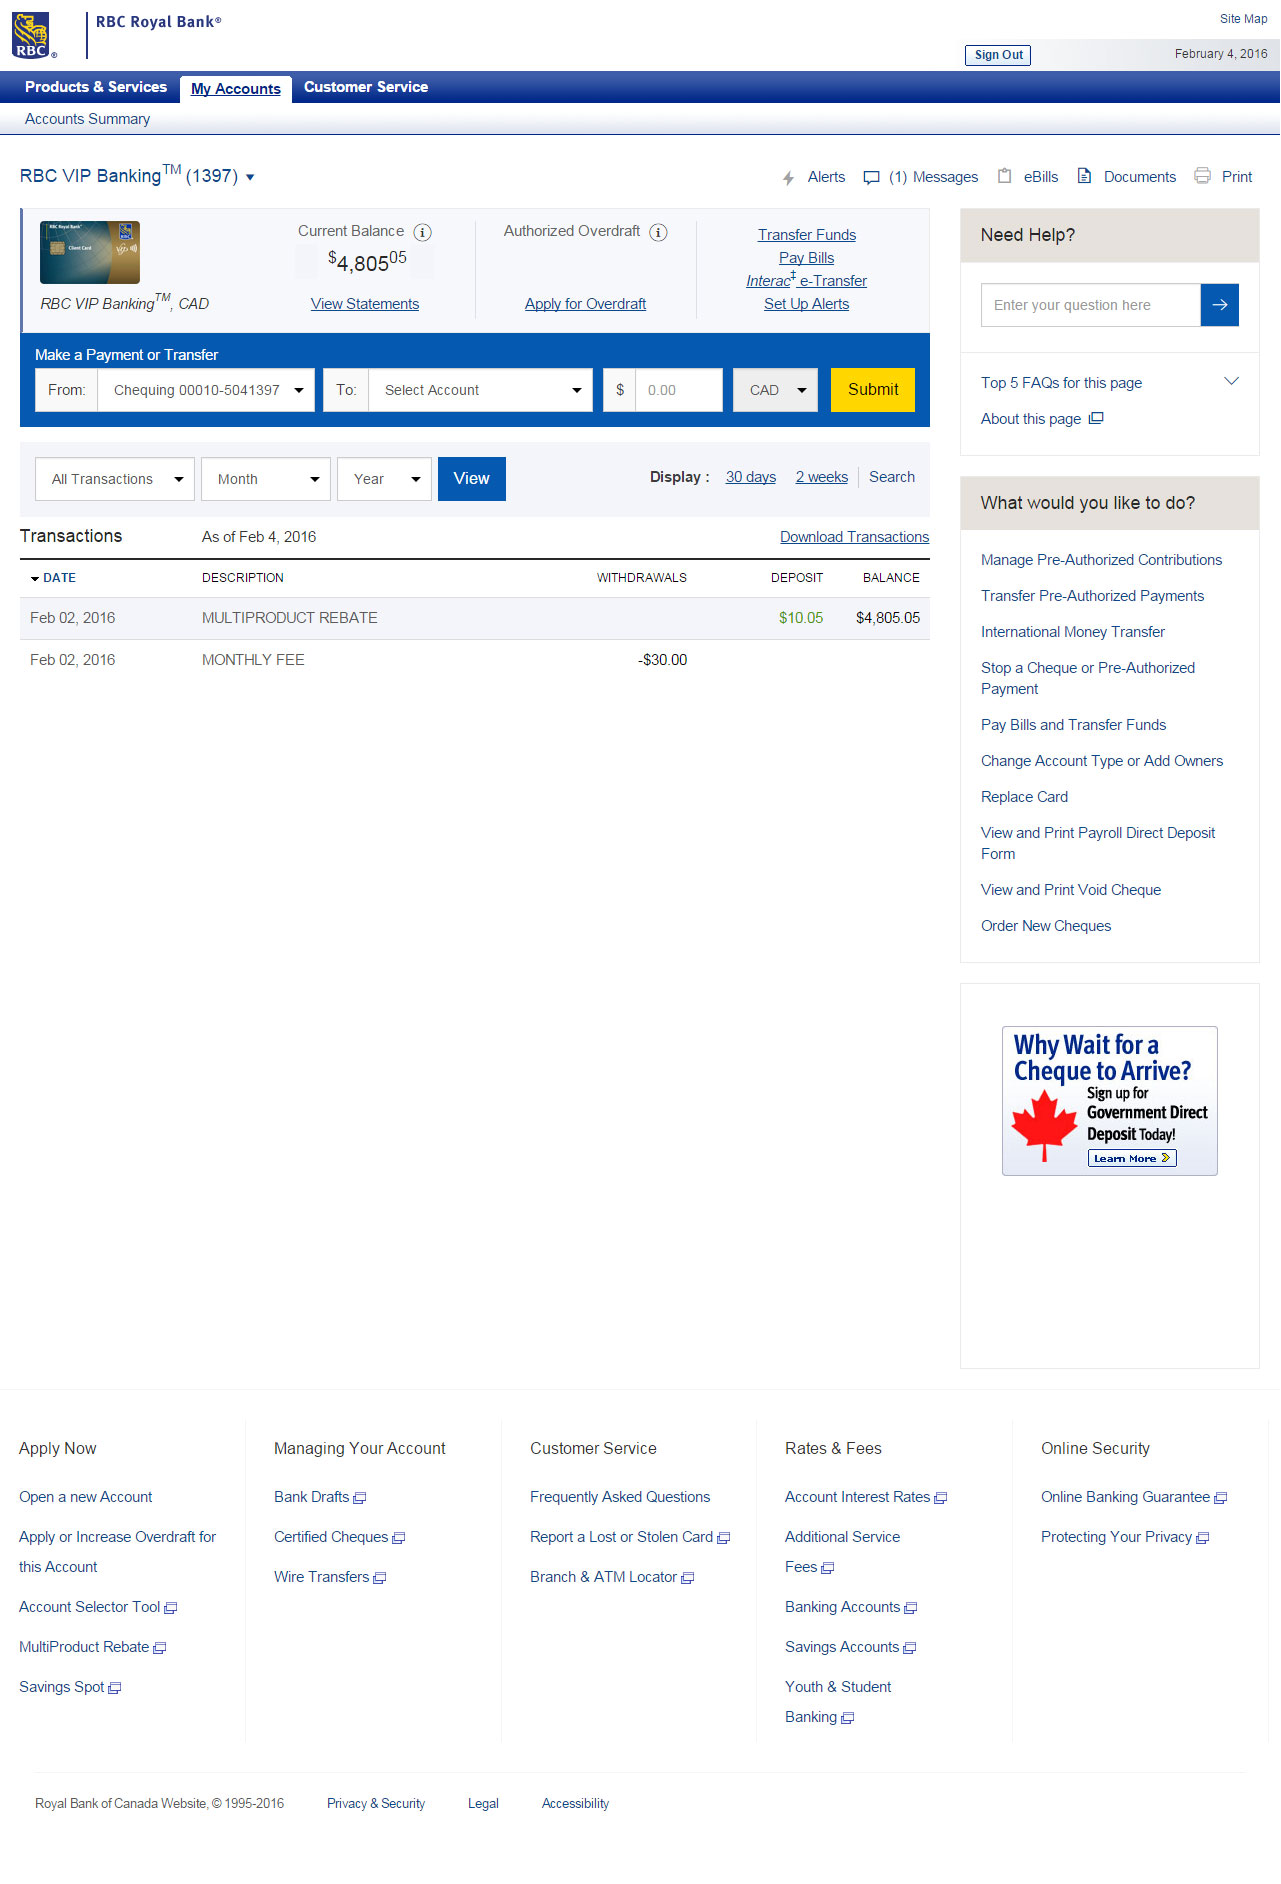
The user experience on RBC Online is engineered for efficiency, yet efficiency often carries hidden costs. Clients can complete most transactions in minutes, but the path to completion is paved with prompts for credit products, insurance upgrades, and investment accounts. These prompts are not neutral; they are calibrated to appear when engagement metrics suggest a user is most receptive.
Consider the dashboard layout, where bill payment sits alongside pre-approved credit offers. The positioning implies that borrowing is a natural extension of managing cash flow, a subtle suggestion backed by behavioral research. As one former digital product manager at a major Canadian bank noted, “The interface is a series of choices designed to maximize engagement and cross-sell, often without the user realizing how many decisions are being steered.”
Behavioral data from RBC Online reveals patterns that align with classic economic theories, but with a digital twist. Time scarcity, for instance, becomes a lever when the platform highlights limited-time offers or countdowns on promotional rates. In practice, this can push clients toward decisions that prioritize immediacy over careful comparison.
- Auto-renewal features for financial products reduce churn for the bank but may lock users into unfavorable terms.
- Personalized notifications, such as “Your spending is above average,” can curb overspending or trigger anxiety, depending on the user’s circumstances.
- Credit score checks triggered during routine logins normalize frequent inquiries, which can subtly lower scores over time.
These dynamics raise questions about consent. Users agree to broad data-use clauses at signup, but few read the full terms. The result is a paradox in which convenience depends on opacity, and empowerment rests on understanding systems that few have the training to dissect.
The impact of RBC Online extends beyond individual choices to broader social outcomes. Credit algorithms, for example, can reinforce existing inequalities by favoring clients with established financial histories. A young professional in Toronto may receive tailored offers that accelerate asset building, while someone in a marginalized area sees fewer opportunities and more high-cost products.
Public-interest advocates have called for greater transparency in how algorithms weight factors like income, location, and spending patterns. Without clear reporting requirements, banks can optimize for profit while externalizing risks onto vulnerable populations. The Canadian Centre for Policy Alternatives has warned that “digital redlining” could become a norm unless regulators demand auditable data on approval rates by demographic group.
Looking ahead, RBC Online is likely to deepen its integration with artificial intelligence and open banking frameworks. That evolution will bring faster approvals, more tailored advice, and potentially more opaque decision chains. Clients who understand the mechanics of the platform are better positioned to resist manipulative nudges and demand fairer design.
For regulators, the challenge is to craft rules that protect consumers without freezing the innovation that drives financial inclusion. For users, the lesson is simple: convenience is not free, and every login leaves a trace that influences future options. The true measure of RBC Online will not be its speed or polish, but whether it expands genuine choice rather than channeling it.
Related Post